Up to $35,000 toward your first Florida home
If you work full-time for a Florida school, hospital, fire department, police agency, court or child care center, or you serve in the military, Hometown Heroes can cover 5% of your loan at 0% interest. The 2026 money is available now, but it's first-come, first-served and last year's funds were gone by February.
Two minutes, free, and nobody pulls your credit. Rather talk? (800) 555-0100
- 5% of your loan, $10,000 minimum, $35,000 maximum
- 0% interest, no monthly payment, repaid when you sell or refinance
- 640 minimum credit score
- Funds reserved only after you have a signed contract
The quick read
Florida Hometown Heroes in four numbers
Florida Housing put $50 million into the 2026 round, which opened July 13, 2026. The help comes as a second mortgage, so think of it as a 0% loan you pay back later, not a grant.
Whose job counts
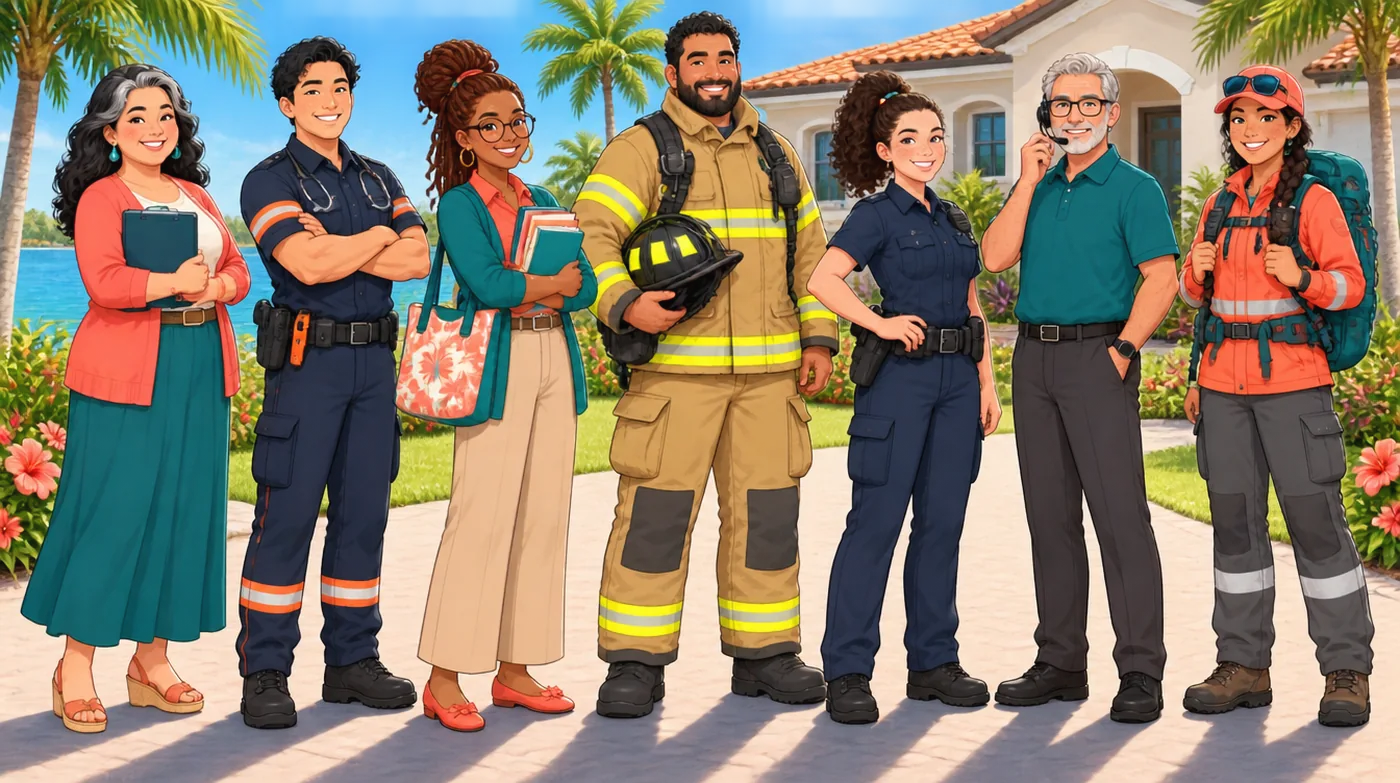
Seven kinds of work open the door
You need to work full-time for one eligible employer at a Florida brick-and-mortar location, or be active military, a reservist or a veteran. Remote workers and offer letters don't count.
Teachers & school staff
Anyone full-time at a Florida K-12 public, private, charter or magnet school, from classroom teachers to cafeteria staff.
Police, deputies & corrections
Sworn officers, deputies, corrections and probation officers, juvenile detention staff and 911 dispatchers.
Firefighters, EMTs & paramedics
Full-time staff of a Florida fire department, ambulance service or hospital.
Nurses & healthcare workers
RNs, LPNs, CNAs, techs, therapists, pharmacists and more at Florida hospitals, clinics and care facilities.
Court employees
Court clerks, reporters, assistant state attorneys and assistant public defenders.
Child care workers
Full-time staff at licensed or license-exempt Florida child care facilities, including home day cares.
Military & veterans
Active duty in any branch, plus reservists and veterans who work full-time in Florida.
The details, sorted
Money, rules, loan and paperwork in one place
Tap a tab. Each one covers a single piece of how Florida Hometown Heroes Housing Program works.
Your down payment options in Florida
Hometown Heroes second mortgage
5% of your first mortgage, at least $10,000 and no more than $35,000. It has 0% interest and no monthly payment for up to 30 years, and you repay it in full when you sell, refinance, transfer the deed, pay off the first mortgage or move out.
Local help on top
Hometown Heroes can't be stacked with other Florida Housing assistance, but stand-alone help from another agency, such as a city or county SHIP program, can sit behind it as a third mortgage. Ask your lender what your county offers.
If your job isn't on the list
Florida Housing has other options: Florida Assist (up to $10,000, 0% deferred), the HFA PLUS second (3% to 5%, forgiven over 5 years) and the FL HLP second ($12,500 at 3% with a monthly payment). None of them combine with Hometown Heroes.
Mortgage Credit Certificate
A Hometown Heroes first mortgage can be paired with an MCC, but Florida Housing doesn't issue one right now. You'd need a local MCC issuer where one is available.
The rules, one at a time
Full-time Florida job
You work full-time (paystubs showing 40 hours, or an employer verification) for one eligible employer at a physical Florida location. Hybrid workers qualify only if they're on site at least three days a week.
First-time buyer
No ownership interest in a home you lived in during the 3 years before closing. Veterans, active military and reservists are exempt, and so is anyone buying in a federally designated targeted area.
Income under your county limit
Limits are set by county and depend on whether your lender uses the TBA or Bond option. See the income limits page.
640 credit score
Every loan type needs at least 640. A manually underwritten loan needs 660.
Homebuyer education
One buyer who will live in the home must finish an approved pre-purchase course before closing. Military and veterans are exempt except on the conventional HFA loans.
Your main home
You must be a Florida resident and move in within 60 days of closing. Purchases only, no refinances.
The loan underneath it
Hometown Heroes help only comes with a Florida Housing first mortgage. Florida Housing sets that rate every day and doesn't post it publicly, so a participating lender quotes it for you.
Loan types
- FHA, VA, USDA and conventional
- 30-year fixed rate
- Conventional HFA Advantage: buyers at or below 80% of area income get a lower rate and reduced-cost mortgage insurance
Costs
- No 1% origination fee and no discount points
- Lender origination fees capped at $1,750
- Program fees: $400 investor funding, $275 compliance, $85 tax service, $10 flood certificate transfer
- The mortgage and note are exempt from Florida documentary stamp and intangible tax (the deed is not)
Qualifying
- 640 minimum credit score
- Debt-to-income up to 50% with an automated approval
- 43% on a manual underwrite (660 credit)
- 45% for manufactured homes
Property
- Single-family homes, townhomes and approved condos
- 2 to 4 units if you live in one
- Manufactured homes, with restrictions
- You can use Florida Housing programs only once
What your lender will ask for
Proof of full-time work
Recent paystubs showing 40 hours, or a written or verbal verification of employment. An employer letter must come from a work email with a signature and list your Florida work address. Offer letters are not accepted.
Military papers
Active duty and reservists: a current Leave and Earnings Statement (LES). Veterans: a DD214 showing a discharge other than dishonorable, plus proof of full-time Florida work.
Income and assets
Your lender will also ask for the usual mortgage paperwork, such as tax returns, W-2s and bank statements.
Education certificate
Your homebuyer education certificate, dated within the last 2 years, unless you're exempt.
Quick math
How much could Hometown Heroes give you?
The assistance is 5% of your first mortgage, not the price of the home. Move the slider to see a rough number for your price range and loan type.
Start to finish
Six moves from pre-approval to keys
- Confirm you work full-time at a Florida location of an eligible employer, or that you're active military, a reservist or a veteran working full-time in Florida.
- Check your county's income limit, and its purchase price limit if your lender uses the Bond option.
- Find a Florida Housing participating loan officer and get pre-approved with a 640+ credit score. There's no fee to apply for Hometown Heroes itself.
- Take an approved homebuyer education course, in person or online. The certificate is good for 2 years.
- Sign a purchase contract. Only then can your lender reserve your Hometown Heroes first and second mortgage.
- Close within 60 days of the reservation (one 30-day extension is allowed). The second mortgage records behind your first.
Find a loan officer who does this every week
Not every Florida lender offers Hometown Heroes. A participating loan officer can see the day's rate, tell you whether they use the TBA or Bond option, check your county limits and reserve funds the moment your contract is signed. With money going first-come, first-served, that speed matters.
County by county
Limits shift as you cross county lines
Income limits run from $148,050 in many smaller counties to $204,300 in Miami-Dade under the TBA option. Pick your county for its numbers.
All 20 county pages · City-run programs · Full limits table · Budget calculator · Statewide directory
Paid another way?
No W-2 doesn't mean no help
Business owners & 1099 earners
Own a business? Here's how lenders see you
Florida lenders qualify business owners on net income from tax returns, averaged over two years. Hometown Heroes needs an eligible employer, but several state and county programs don't.
- FHA uses the lower of your 2-year average or latest year
- Florida Assist and county SHIP programs have no job test
- A teacher or nurse spouse can still bring Hometown Heroes
Rideshare, delivery & app-based work
Paid by the apps? Lenders read your Schedule C
Rideshare, delivery and Flex income can qualify in Florida, but lenders count net profit after mileage, not your weekly payouts.
- Plan on about 2 years of app income history
- Weekend gigs don't block Hometown Heroes for hero jobs
- Florida Assist and county programs skip the job test
Asked and answered
What buyers ask us about Florida Hometown Heroes Housing Program
Is Florida Hometown Heroes available right now?
Yes. The 2026 round, funded with $50 million in the state budget, opened July 13, 2026. It runs first-come, first-served until the money is committed, and there's no set end date. We couldn't verify a live balance from Florida Housing, so ask a participating lender to confirm funds are still available.
How fast does the money run out?
Fast. The previous $50 million round opened in August 2025 and was fully committed by February 2026. A third-party report in September 2026 put the remaining 2026 funds at more than $25 million, but that number changes daily.
How much can I get?
5% of your first mortgage, with a $10,000 minimum and a $35,000 maximum. A loan of $200,000 or less gets $10,000, and you reach the $35,000 cap at a $700,000 loan.
Is it a grant?
No. It's a 0% interest, 30-year deferred second mortgage. There's no monthly payment, but it isn't forgiven. You repay the full amount when you sell, refinance, transfer the deed, pay off the first mortgage, stop living in the home, or at the end of the 30 years.
Which jobs qualify?
Full-time employees of Florida-based K-12 schools, hospitals and healthcare providers, fire departments and ambulance services, law enforcement, corrections and emergency operations centers, courts and prosecutor or public defender offices, and licensed child care facilities. Active military, reservists and veterans qualify too. See who qualifies.
Can I work remotely or part-time?
No. You need one full-time job at a physical Florida location. Hybrid workers qualify if they're on site at least three days a week. Fully remote workers, retirees and people stacking part-time jobs don't qualify.
I owned a home before. Can I still apply?
Only if you haven't owned and lived in a home in the past 3 years, unless you're exempt. Veterans, active military and reservists, and buyers in federally designated targeted areas don't have to meet the first-time rule.
What are the income limits?
They depend on your county and on the option your lender uses. Under TBA, one limit covers any household size, from $148,050 in many counties up to $204,300 in Miami-Dade. Under Bond, limits depend on household size and there's a price cap too. See income limits.
What's the interest rate?
Florida Housing sets a 30-year fixed rate daily and only shows it to participating lenders, so we can't quote it here. There's no 1% origination fee and no discount points. A participating lender confirms today's rate.
How do I apply?
Through a Florida Housing participating lender, not the state directly. Get pre-approved, take a homebuyer course, sign a contract, and your lender reserves the funds. Check your eligibility and we'll connect you with a loan officer who offers the program.
Get in line before the money's gone
Two minutes, no credit pull. A loan officer who offers Hometown Heroes will follow up with your real numbers.